
Can I get OAS before 65? The age rule and what is available at 60
Short answer
Can I get OAS before 65? No. The Old Age Security pension cannot start before age 65, and there is no reduced early option like CPP has. Between 60 and 64 the only OAS-program payments are the Allowance, for low-income spouses of GIS recipients, and the Allowance for the Survivor. CPP is the public pension you can start at 60.
- 01Earliest OAS start
- Age 65
- 02Latest OAS start
- Age 70, with up to 36% more
- 03Allowance, ages 60 to 64 (Oct to Dec 2026)
- Up to $1,448.06 a month
- 04Allowance for the Survivor
- Up to $1,726.18 a month
- 05Earliest CPP start
- Age 60, reduced up to 36%
Can I get OAS before 65? The age 65 rule
Service Canada is direct about this: you must be 65 or older to receive the Old Age Security pension. There is no application, hardship route or early-retirement option that pays the OAS pension at 60, 62 or 64.
So the answer to "can I get OAS at 60" is no, even if you have lived in Canada for 40 years and stopped working. What you can do before 65 is get your paperwork in order so the first payment arrives in the month after your 65th birthday, and check whether one of the two Allowances applies to you.
Why there is no early OAS, unlike CPP
CPP is an earnings-based plan you pay into, and it lets you trade a smaller cheque for an earlier start. OAS is funded from general tax revenue and based on residence, and the law sets 65 as the first possible month. The only flexibility is in the other direction: you may delay.
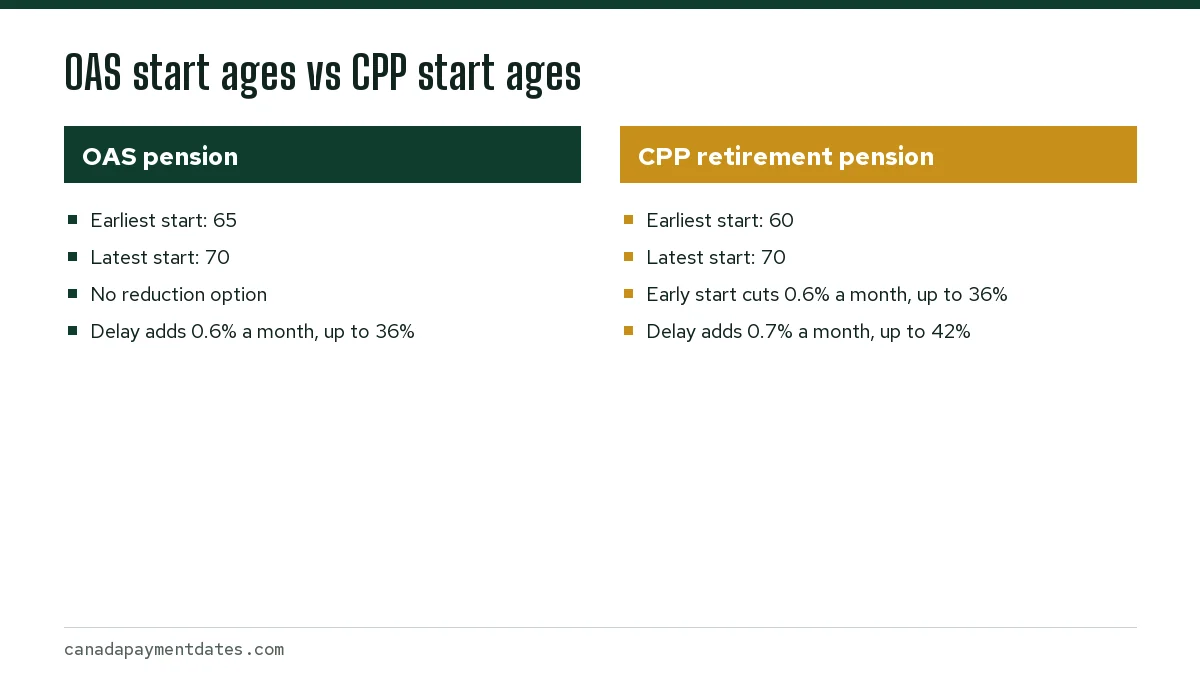
Delaying OAS adds 0.6% for each month after 65, or 7.2% a year, up to 36% at 70. At the October to December 2026 rate, a full $762.50 pension would be about $1,037.00 a month if started at 70, before any cost-of-living increases in between. GIS is not paid during a deferral, so low-income seniors usually lose more than they gain by waiting. See OAS deferral for the trade-offs.
The Allowance at 60 to 64
The Allowance is the closest thing to early OAS, but it is narrow. It is meant for a low-income person whose spouse or common-law partner is already on OAS and GIS.
- You are 60 to 64.
- Your spouse or common-law partner receives OAS and is eligible for GIS.
- You have lived in Canada for at least 10 years since turning 18.
- Your combined annual income is under $42,768 (October to December 2026).
- You are a Canadian citizen or legal resident and not under a sponsorship agreement, apart from the listed exceptions.
The maximum Allowance for October to December 2026 is $1,448.06 a month. That is exactly the full OAS pension ($762.50) plus the maximum GIS for someone whose partner gets OAS ($685.56). In effect, the Allowance pays a low-income couple as if both partners were already 65.
If your spouse has died
Widows and widowers aged 60 to 64 who have not remarried or entered a new common-law relationship may qualify for the Allowance for the Survivor, worth up to $1,726.18 a month for incomes under $31,152.
CPP as the early option
If you need a public pension before 65 and do not qualify for either Allowance, CPP is the route. You can start CPP at 60 with a reduction of 0.6% for each month before 65, up to 36%.
Using the 2026 maximum of $1,507.65 at 65, a person entitled to the maximum who starts at 60 would get 64% of it, about $964.90 a month. Most people are entitled to less than the maximum; the 2026 average at 65 was $877.01. The CPP at 60 page walks through the decision.
OAS at 64: applying so payments start on time
The year you turn 64 is when the OAS process actually begins. Service Canada sends an enrolment letter around your 64th birthday if it has enough information to enrol you automatically.
- Watch for the enrolment letter around your 64th birthday. If it confirms automatic enrolment, check the details and do nothing else unless you want to delay.
- If a month has passed since your 64th birthday with no letter, apply online in My Service Canada Account or on form ISP-3550, Application for the OAS and the GIS.
- To start later than 65, choose Delay Receiving OAS/GIS Pension under Profile in My Service Canada Account, or contact Service Canada.
- Make sure your direct deposit details are current so the first payment lands on schedule.
- Keep filing a tax return every year; OAS and GIS both depend on it.
Once OAS starts, it is paid on the same dates as CPP. The remaining 2026 dates are October 28, November 26 and December 22; the full calendar is on our OAS payment dates page, and current rates are on OAS payment amounts.
Common questions
Can I get OAS at 60?
No. The OAS pension starts at 65 at the earliest. At 60 to 64 you may qualify for the Allowance or the Allowance for the Survivor, and you can start CPP.
Is there an early OAS option like CPP?
No. CPP can start at 60 with a reduction, but OAS has no reduced early start. You can only delay OAS, up to age 70, for a larger payment.
What is the Allowance for people aged 60 to 64?
A monthly, tax-free payment for low-income people aged 60 to 64 whose spouse or common-law partner receives OAS and is eligible for GIS. It is worth up to $1,448.06 a month for October to December 2026.
When should I apply so OAS starts at 65?
Watch for the enrolment letter around your 64th birthday. If none arrives within a month after that birthday, apply online or with form ISP-3550.
Does the Allowance turn into OAS at 65?
The Allowance stops when you turn 65. From then on you receive the OAS pension and, if your income is low enough, GIS.
Sources
- Old Age Security: Do you qualify canada.ca
- Old Age Security: When to start canada.ca
- Allowance: Do you qualify canada.ca
- CPP: When to start canada.ca
- Old Age Security: Apply canada.ca
We check figures against these official pages. Rules change; confirm anything that affects a deadline or payment with the agency before you act.
Tell us what happened
Describe your situation and our editors will use it to improve this guide. If you leave your email, we may reply with a pointer to the right page or official contact. We never share your details.
Related guides
 OAS Payment Dates: 2026 Schedule, GIS and Current Amounts
The next OAS payment date is Wednesday, October 28, 2026, the first at the higher October to December rates, followed by November…
How Much Is OAS per Month? October to December 2026 Rates
How much is OAS per month? For October to December 2026, the full Old Age Security pension is up to $762.50 a month at ages 65 to…